High Net Worth Equal Family Business Profits Division
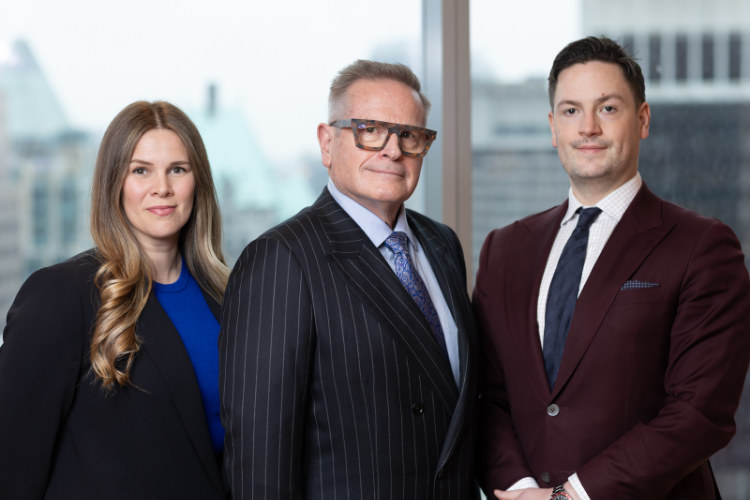
MacLean Law’s High Net Worth Equal Family Business Profits Division has set a precedent for Canadian family property cases. Under the Family Law Act upon separation both spouses have a prima facie undivided one half share in family property as a tenant in common. Unfortunately, many family lawyers failed to address the urgent need for an equal division of family business profits before trial to ensure these profits are not misused as a personal “piggy bank” by one of the spouses. A team Of Lorne MacLean KC, Sophie Bartholomew and Jesse Emmond succeeded in an equal division of family business profits the court found the husband had in part used as his personal “piggy bank”. Madsen v. MacNutt is a case of first instance with huge implications for wealthy separated spouses. Contact our Winning High Net Worth Equal Family Business Profits Division lawyers if you have a high net worth case involving a business, a venture or a professional practice. This latest win follows MacLean’s record spousal and child support wins of over $100,000 monthly for a woman, record spousal support for a man at $30,000, precedent setting worldwide family Mareva injunctions, record fines and record jail time for spouse’s failing to comply with court orders. In today’s blog Lorne MacLean KC explains how he won this key case.
Vancouver High Net Worth Equal Family Business Profits Division Tel: 604 602 9000
In a marriage of 15 years spousal support would have totaled under $10,000 per month from a family business the Court found had been used as a “piggy bank” since separation by the husband. Lorne MacLean KC founder of our winning High Net Worth Equal Family Business Profits Division team argued that our client was a key partner in expanding the lucrative family business and that section 91 and SCFR Rule 12-4 should be applied to divide profits equally before trial to level the playing field and prevent mischief. The net result was that for the first time ever in BC an interim pre-trial equal division of family pretax profits was ordered.
Why should UHNW spouses care? The net result was our client received $1,250,000 retroactive division over 18 months being $69,444 a month versus support that would have been less than $10,000 a month.
Here is what Justice Ahmad of The BC Supreme Court found:
89] I am satisfied that in the period between August 2025 and May 2026, the respondent has caused the Company to pay for his personal expenses of approximately $1 million ($515,000 + $225,000 + $265,000). Extrapolating that amount to August 31, 2026 results in estimated personal expenditures from the Company account of approximately $1,250,000. With no apparent means by which to repay those funds, I have no difficulty in concluding that the respondent has used, and continues to use, Company funds—to use the words of the Court in Valastiak and Perera—as his personal “piggy bank”.
[90] The personal expenditures in excess of $1 million are extraordinary, even in absolute terms. They are more extraordinary considering that the Company had just $471,000 of cash on hand and $1.3 million of net earnings from operations when the payments began. They are also quite remarkable given the respondent’s forecast of negative cash flow and his current assertion of the Company’s precarious financial position (the details of which I discuss further below).
[91] In those circumstances, I have no difficulty concluding that the respondent gave little, if any, consideration to the Company’s financial position when he caused the payments to be made for his own personal benefit. Rather, he chose to deplete Company funds that would otherwise have been available for the Company’s business operations for his own personal needs.
[92] Especially in light of what the respondents assert is the Company’s precarious financial position, I have no difficulty concluding that the respondent’s use of Company funds for his personal expenses may well have jeopardized the Company’s ability to continue to operate at capacity, let alone to grow its business. It amounts to conduct that may affect Company value and defeat or adversely affect any interest in the shares to which the claimant may be entitled. The requirements for consideration for an order to vest a portion of the Company’s pre-tax income in the applicant under s 91(2) have been met.
Victoria High Net Worth Equal Family Business Profits Division Tel: 604 602 9000
High Net Worth Equal Family Business Profits Division Lawyers, MacLean, Bracken, F. MacLean and J. Emmond
The court went on to find the wife’s argument for equal division should be made and a total of $1,250,000 retroactive business profit division was ordered together with AN EQUAL SHARE of family business profits pending trial.
[101] As the final consideration on this analysis, I have considered that the value of the property to which the claimant asserts a claim is not limited to the Company. It also includes the value of all of the Family Businesses and their real estate holdings. The respondents estimate that value to be $43 million; the claimant’s estimate, at approximately $140 million, is considerably higher.However, even the respondent’s estimate results in more than sufficient value in the family property to answer the claim to an equal payment of the post-separation Company profits. That conclusion value satisfies the requirement for the granting of an order under Rule 12-1.
[102] On the other hand, the respondent argues that the combined value of the family property weighs against the payment of funds to the claimant on an interim basis. He argues that given that value, and with certificates of pending litigation registered against title to the properties, there is no (or little) risk that the claimant will be deprived of any monetary award, including her claim to the Company profits, to which she may be entitled at trial.
[103] In the circumstances, that argument is not compelling.
[104] The argument ignores that the claimant’s claim is not limited to a monetary interest, that is, the increase in the value of the Company. She also claims an interest in the Company itself. Arguably, given the respondent’s significant depletion of Company funds, by the time of trial, there may well be no Company at all. By the same token, if the Court determines that the claimant’s interest is limited to the increase in value, it is reasonably possible that the respondent’s use of Company funds may result in the Company having no (or significantly less) value on which to base that award.
[105] Whatever the claimant’s entitlement, it is significant that the respondent has unilaterally taken the immediate benefit of more than $1 million to which both parties have claimed an interest directly from the Company. The claimant, on the other hand, would have to wait until the parties’ interests are determined at trial to claim any amount to which she may be entitled. If successful, she may be left with the uncertainty and delay in having to recover against other property.
[106] In my view, that outcome is unjust. Arguably, given her 15-year tenure as controller, the claimant has contributed to the Company, including to the increase in profits and (likely) its value. By contrast, in the time that the respondent has taken over the leadership of the Company, he has, arguably, contributed to its financial decline.
[107] I am satisfied it is appropriate to order that the respondent shall cause, and the Company shall pay to the claimant, the sum of $1,250,000 (that being the amount of the respondent’s anticipated personal expenditures from August 2025 to date).
Kelowna High Net Worth Equal Family Business Profits Division
If you have a ultra high net worth family business, joint venture of professional practice profit dispute contact our winning High Net Worth Equal Family Business Profits Division lawyers.